Pagani equity release
Pagani equity release is a loan secured against a Pagani you already own. The car stays with you and you carry on driving it. A lender advances a share of what it is worth, takes security over it for the term, and releases the money to you or into your business.
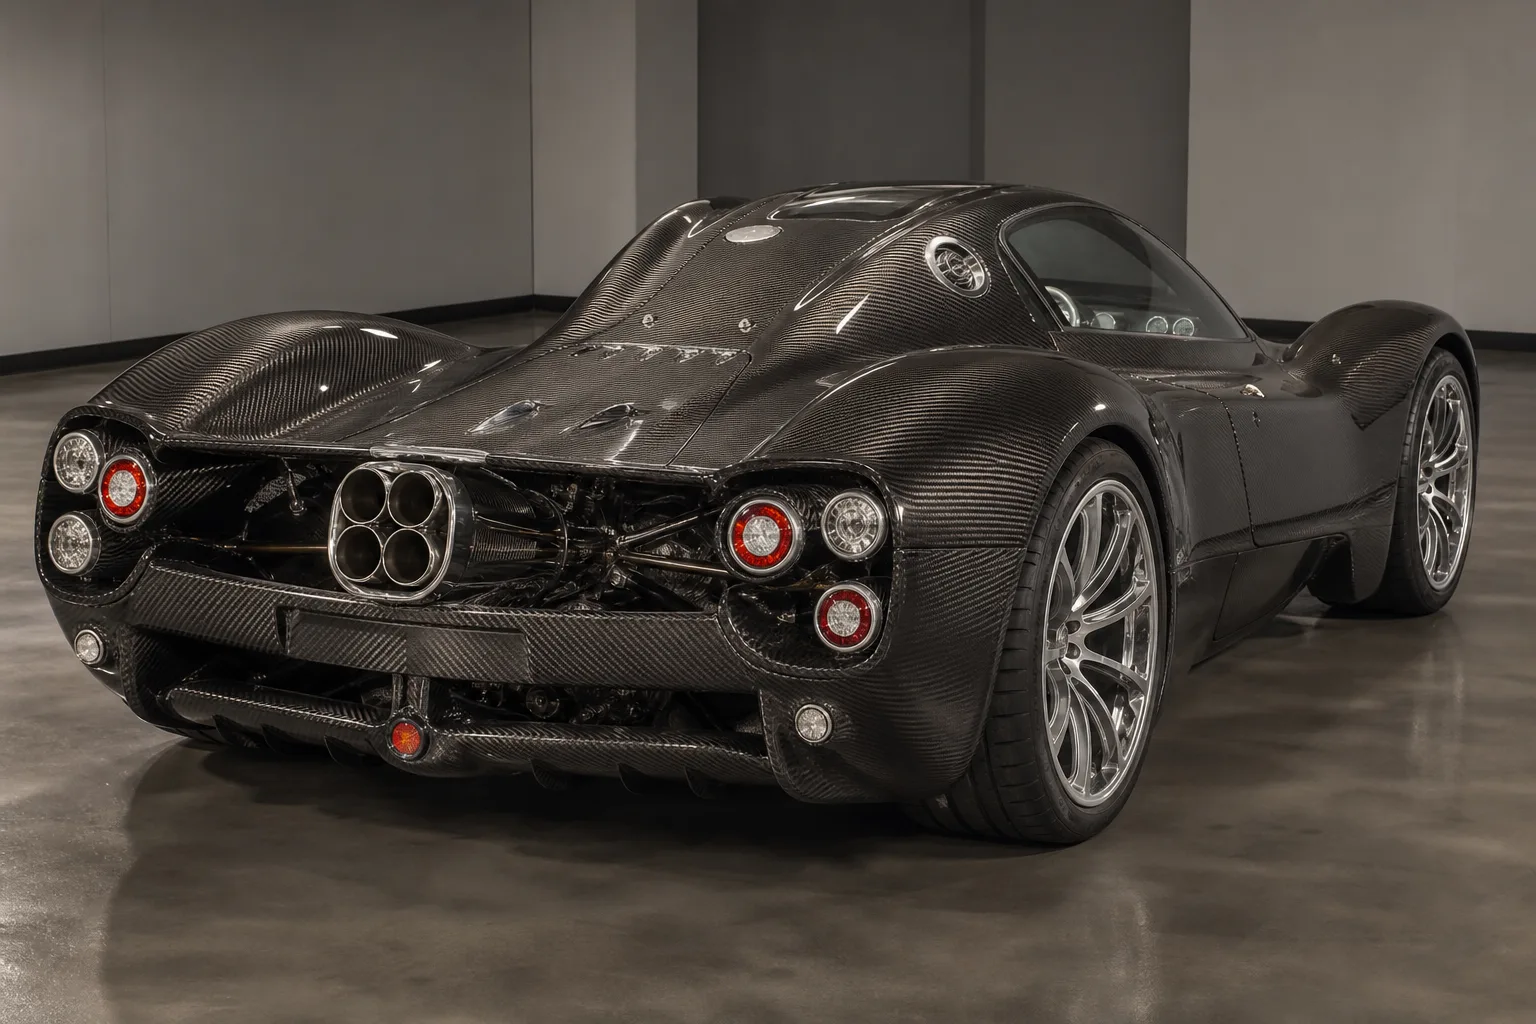
- Models covered
- 5
- Value range
- £1,800,000 to £5,400,000
- Still in production
- 1 of 5
- Typical advance
- 50 to 70%
- Built in
- San Cesario sul Panaro
- Rate
- 8.9%
- Paid over
- 48 months
- Advance
- 50 to 70% of value
- Minimum
- None
An estimate, not a quote. Nobody has assessed your circumstances or seen your car yet.
What does Pagani equity release actually mean?
Pagani equity release is a loan secured against a Pagani you already own. The car stays with you and you carry on driving it. A lender advances a share of what it is worth, takes security over it for the term, and releases the money to you or into your business.
The distinction that matters is between this and buying a car. Ordinary car finance pays a dealer and you end up with a car. This runs the other way: you already have the Pagani, and the finance turns part of what it is worth back into money you can use. Nothing is sold, nothing is handed over, and the car does not go anywhere.
We arrange it and we are not a lender. There is no minimum advance and no maximum, and the Pagani range we cover runs from £1,800,000 to £5,400,000, so the sums involved differ by a factor of 3 across the 5 models on this page alone.
How much equity is there in a Pagani?
Equity in a car is what it is worth now, less anything still owed on it. Own a Pagani worth £2,400,000 outright and the equity is £2,400,000. Owe £720,000 against the same car and the equity is £1,680,000. That subtraction is the whole calculation, and it is worth doing before you speak to anybody.
Positive equity means the car is worth more than the debt against it, and it is the position you need to be in for any of this to work. Negative equity means the debt exceeds the value, which happens on cars that fall faster than the balance does, and no amount of restructuring releases money from a car in that position. It can still be worth refinancing to reduce a payment, but that is a different piece of work and we will say so rather than take you through an application that cannot end well.
A lender does not advance the whole of the equity. Expect 50 to 70 per cent of the car's value as the working band, which on a £2,400,000 Pagani is £1,200,000 to £1,680,000 before anything owed is deducted. The gap between the value and the advance is the lender's margin for the cost and the uncertainty of selling the car if the payments stop.
What decides how much a Pagani will release
Four things, in roughly this order: what the car is, what condition it is in, what the paperwork looks like, and who is borrowing. The model matters less than owners expect, because a lender is pricing your specific car rather than the name on it.
On this marque the age spread does most of the work. 1 of the 5 Pagani models here are still in production and 4 are not, with the oldest running back to 2009. A car still being built has a live market and a value a lender can check in an afternoon. A car out of production for years is valued from what comparable examples have actually achieved, which takes longer and rewards a complete history file.
Mileage, service history, originality and specification all move the figure, and on a Pagani the specification can move it a long way. So can the number of owners and whether the car has been kept in the United Kingdom. None of this is unusual to be asked about, and having it ready shortens the process considerably.
Every Pagani we release equity against
All 5 Pagani models below, with an indicative value and the band a lender would typically advance against it. Every one of them is in the same class of car, which keeps the valuation approach consistent across the range.
Read these figures as indicative and nothing more. They are the market position for the model, not a valuation of your car, and no lender has seen it. A Imola at £5,400,000 and a Huayra at £1,800,000 sit at opposite ends of what Pagani ownership costs, and the sum releasable differs accordingly.
- Pagani Utopia 2023 to date6.0L V12 Twin-Turbo, 864 bhp£2,400,000
- Pagani Huayra Roadster BC 2019 to 20206.0L V12 Twin-Turbo, 800 bhp£3,400,000
- Pagani Huayra 2012 to 20186.0L V12 Twin-Turbo, 730 bhp£1,800,000
- Pagani Zonda Cinque 2009 to 20107.3L V12 Naturally Aspirated, 678 bhp£2,000,000
- Pagani Imola 20206.0L V12 Twin-Turbo, 827 bhp£5,400,000
How Pagani equity release is arranged
Four steps, and the first one is short. We ask what the Pagani is, what you believe it is worth, what is still owed on it and what the money is for. That conversation establishes whether there is a deal at all, and it happens before anything touches your credit file.
We then approach the lenders whose appetite fits rather than all of them, because a credit file full of searches is worth less than a clean one, and the lenders who will advance against a car out of production are not the same ones who write ordinary motor finance. You see the terms in writing, with the total cost across the term and the early settlement position set out rather than buried.
The lender then values the car, which on a Pagani usually means an inspection rather than a desk exercise. Documents follow: identification, proof of ownership, the service history, and for a company application the filed accounts and bank statements. Security is registered, the money is released, and the car stays exactly where it is.
What Pagani equity release costs
Take a Pagani at £2,400,000, owned outright, with £1,680,000 released against it at 70 per cent of value. Over 48 months at an indicative 8.9 per cent, that is about £41,727 a month, and £2,002,903 in total across the term.
That total is the number to look at, and it is the one most comparisons leave out. Two offers at the same monthly payment can differ by a substantial sum once the term length, the fees and the early settlement terms are set beside each other. A longer term always looks cheaper monthly and is almost always dearer overall.
The rate itself follows the car, the borrower and the loan to value. Ask for 50 per cent of the value rather than 70 and the rate generally improves, because the lender's exposure falls. That trade is usually worth more than negotiating the rate directly.
Pagani finance beyond releasing equity
Releasing capital against a Pagani you own is one job. Buying one is a different job, with different lenders and a different set of agreements, and we cover it separately at Pagani finance. If you are weighing whether to release equity from the Pagani in the garage or to finance the next one, it is usually worth reading both, because the two are frequently arranged together as a single piece of work: the equity in the current car becomes the deposit on the next.
Pagani has built cars in San Cesario sul Panaro across the 5 models on this page, and a lender will treat a Imola at £5,400,000 very differently from a Huayra at £1,800,000. Tell us which one is yours and the conversation starts from the right place.
Pagani equity release questions
- Can I release equity from a Pagani I still owe money on?
- Yes, provided the Pagani is worth more than the outstanding balance. The existing agreement is settled out of the new advance and the difference is released to you, so what you receive is the equity less the settlement figure. Ask your current lender for a settlement figure before you start, because that number, not the balance on your statement, is what the arithmetic actually uses.
- How much can I release from a Pagani?
- Typically 50 to 70 per cent of what the car is worth, less anything still owed on it. Across the 5 Pagani models we cover, values run from £1,800,000 to £5,400,000, so the advance ranges from roughly £900,000 at the bottom of the range to £3,780,000 at the top. Your car decides where in that band it sits.
- Do I have to give up the Pagani?
- No. You keep the car and you drive it exactly as before. The lender registers security over it, which means it cannot be sold with the finance outstanding, but possession does not change and nothing about the car's day to day use is affected.
- Is this the same as equity release on a house?
- No, and the difference matters. Property equity release means a lifetime mortgage or a home reversion plan, secured on a home, and it is a regulated product we neither offer nor advise on. This is car equity release: a loan secured against a vehicle, over a fixed term, with a monthly payment. The only thing the two share is the phrase.
- Can a limited company release equity from a Pagani?
- Yes, and it is a large share of what we arrange. The agreement is written in the company name, the lender underwrites the company rather than only the individual, and a director's guarantee is common. Where the car is owned personally and the borrowing is corporate, the ownership has to be sorted out first. The tax treatment and any benefit in kind position are questions for your accountant.
- Will releasing equity from a Pagani affect my credit file?
- The advance appears on your credit file as secured borrowing, in the same way any finance agreement does. What does not have to appear is a trail of applications: we establish appetite with lenders before anything is submitted, so a case that was never going to work does not leave a search behind it.
Values on this page are indicative market positions for the model, taken from our own dataset and checked rather than warranted. They are not list prices, they are not offers, and they are not a valuation of your car. A lender establishes that figure after seeing it. Performance figures are published for identification only. We are not a Pagani dealer and we cannot sell you the car.
Find out what your Pagani will release
Tell us what the car is and whether anything is still owed on it. We come back with what a lender is likely to advance against it and what that would cost to service. If the answer is that it does not work, that is the answer you get.